

Overview
Omnichannel operations represent a transaction model that allows merchants to manage transactions originally initiated outside standard SIBS Payment Gateway checkout channels.
Unlike traditional payment flows, where the transaction is created directly through SPG checkout integrations, Omnichannel operations allow merchants to perform operational actions on transactions that may have originated through other SIBS channels such as:
- Traditional POS
- xPOS
- SmartPOS
- softPOS
This model extends operational flexibility by allowing merchants to centralize transaction management across multiple payment channels through a unified API layer.
Omnichannel operations are currently focused on post-transaction management activities rather than payment initiation.
What Are Omnichannel Operations
Omnichannel operations allow merchants to interact with transactions that were not originally created through standard SPG checkout flows.
This model enables merchants to:
- Perform refunds on externally initiated transactions
- Retrieve transaction status information
- Maintain operational consistency across multiple payment channels
- Centralize transaction lifecycle visibility
From a technical perspective, the original payment may be initiated outside the standard SPG integration model, while operational actions are later performed through SIBS Payment Gateway APIs.
The SPG transactionID should be treated as the primary and authoritative identifier for transaction monitoring, operational correlation, refund execution, reconciliation, and status operations. Originating channel references should be retained where required to support cross-channel traceability and operational correlation.
When to Use Omnichannel Operations
Omnichannel operations are appropriate when merchants operate across multiple payment acceptance channels and require centralized operational management.
Typical scenarios include:
- Physical store transactions processed through Traditional POS or SmartPOS
- Mobile point-of-sale transactions
- softPOS transactions
- Unified commerce environments
- Merchants operating both online and offline channels
- Centralized refund management across multiple payment origins
They are not intended to replace standard checkout integrations for online payment acceptance.
Supported Operations
Within the current SIBS ecosystem, Omnichannel capabilities support:
- Refund operations (see D.4.1 – Omnichannel Refund)
- Omnichannel transaction status retrieval (see D.4.2 – Omnichannel Transaction Status)
These operations are performed after the original transaction has already been processed through another channel.
Payment initiation itself remains outside the Omnichannel operational scope.
Execution Model
The Omnichannel model introduces a different execution pattern from traditional payment flows.
Standard payment models typically follow:
- Customer payment initiation
- Payment authorization
- Payment completion
Omnichannel operations typically follow:
- Original transaction initiated through another channel
- Transaction completed outside SPG checkout
- Merchant performs operational action through SPG Omnichannel APIs
This creates a model where transaction execution and transaction management may occur across different channels.
Transaction Lifecycle
The following diagram illustrates the generic operational lifecycle commonly followed by Omnichannel payment transactions in SPG.
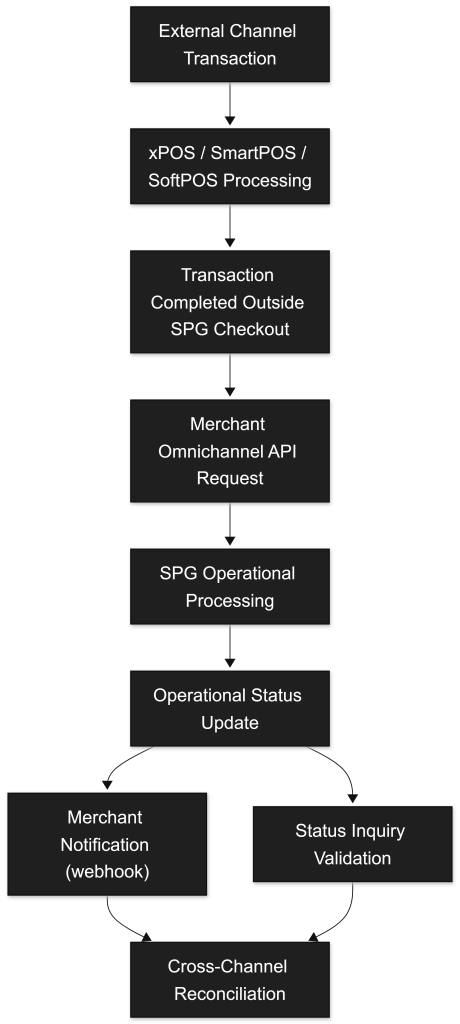
Omnichannel operations typically follow this lifecycle:
- Original transaction initiation through an external SIBS payment channel
- Transaction processing and completion within the originating channel
- Merchant operational request initiation through SPG Omnichannel APIs
- SPG operational processing and validation
- Cross-channel transaction lifecycle synchronization and operational status handling
- Final operational confirmation through the operation response, Merchant Notification (webhook), when configured, or Status Inquiry where additional confirmation is required
- Cross-channel reconciliation and operational monitoring
Depending on the operation being performed, additional status verification may be required.
Advantages of the Omnichannel Model
From a merchant perspective, Omnichannel operations provide:
- Centralized operational management
- Cross-channel transaction visibility
- Simplified refund processes
- Operational consistency across physical and digital channels
- Reduced fragmentation across payment infrastructures
- Centralized operational reconciliation across heterogeneous payment channels
This model is particularly valuable for merchants operating unified commerce strategies.
Particularities in the SIBS Context
When working with Omnichannel operations in SIBS SPG, several platform-specific considerations should be understood:
- The original transaction may not have been created through SPG checkout APIs
- Transaction identifiers and cross-channel operational references must be preserved consistently across systems to guarantee accurate reconciliation and operational traceability
- Operational permissions may vary depending on merchant configuration
- Refund eligibility may depend on the original transaction state
- Omnichannel transaction status visibility depends on the information provided by the originating channel
Proper transaction correlation across systems is critical to ensure operational consistency.
For transaction lifecycle monitoring and operational status validation, refer to E.2 – Status Inquiry / Get Status.
For webhook delivery and asynchronous operational notifications, refer to E.1 – Webhooks (Notifications).
Practical implementation examples, Postman collections, operational workflows, and Omnichannel testing scenarios are documented in F. Technical Examples and Best Practices.
Omnichannel vs Other Payment Models
To position Omnichannel operations within the broader ecosystem:
| Model | Description |
|---|---|
| One-Off | Single transaction initiated directly through SPG |
| Recurring | Repeated merchant-initiated transactions |
| Two-Step | Authorization followed by later capture |
| Omnichannel | Operational actions performed on externally initiated transactions |
This section focuses exclusively on Omnichannel operational models.
For standard checkout payment flows initiated directly through SPG, refer to D.1 – One-Off Payments.
For recurring payment models and Merchant Initiated Transactions (MIT), refer to D.2 – Recurring Payments.
For authorization and delayed capture operational models, refer to D.3 – Two-Step Payments.
Integration Context
In the SIBS Payment Gateway, Omnichannel operations typically require:
- Original transaction identifiers and cross-channel transaction references
- Server-to-server API communication
- Operational authorization controls
- Cross-system transaction reconciliation
These operations are implemented exclusively through server-to-server backend integrations and do not involve customer-facing checkout interactions.
Detailed operational flows are covered in:
Summary
Omnichannel operations extend the SIBS Payment Gateway beyond traditional payment initiation by allowing merchants to manage transactions that originate through external payment channels.
They provide greater operational flexibility and centralized operational governance for merchants operating across multiple commerce environments while maintaining centralized control over key post-payment actions.
Understanding this operational model is essential before implementing Omnichannel refund and transaction status workflows.